Exiting a “Time and Place” Business

“The purpose of middlemen in the marketplace is to provide time and place utility.” I remember the light bulb going on in Economics 101 when my professor said that.  Suddenly, I understood the concept of added value. Someone had to get the product to the customer.

“After all,” the professor continued, “The footwear manufacturer in Massachusetts can’t sell a pair of shoes directly to someone in California. They can’t manufacture and handle thousands of customers. It would be a nightmare, and completely unprofitable.”

The fact that Massachusetts was still known for shoe manufacturing gives you some idea of how long ago this took place. So long ago, in fact, that Zappos wasn’t even a word yet.

The independent shoe retailer gave way to the department stores. In turn their shoe business was decimated by the specialty chain retailers. In fact, most shoe departments in Macy’s and others are actually chain operations within the store. Shoe sales moved into sporting goods stores and discounters. While the industry shifted multiple times, they all still provided time and place utility.

Then came the Internet. Now the manufacturer can sell directly to consumers. In fact, they can eliminate several layers of middlemen, along with the mark-ups.

Lately my area has been swamped with billboards saying “Mattress Dealers are Greedy. TN.com.” TN.com turns out to be Tuft and Needle, a direct selling (via Internet) manufacturer of mattresses. Their pitch is based on eliminating the middlemen. They have diagrams for their supply chain (From us to you.) on the website, along with a list of the markups in the “other guys” logistic chains.

Providing time and place convenience to consumers is challenging when your competitor’s time offering is 24 x 7 x 365 and the place where they purchase is their own home. Even when you need something “right away” online vendors will deliver in as little as two hours.

Last December my wife went out early on a Sunday morning to, “Pick up a few last gifts in time to ship them.” She returned an hour later, empty-handed. “This is ridiculous,” she said. “I’m going to finish my shopping on the Internet, and have all the gifts shipped for me.”

There’s an additional issue when it comes to selling time and place businesses. Many of the new generation of business buyers, the Millennials, value their personal freedom above financial opportunity. They have little interest in coming in early to open up, or staying late to close. Skipping the Thanksgiving family dinner to prep the store for Black Friday is a non-starter.

If you are hoping that I will reveal the secret sauce for perpetuating a time and place business, I’m afraid I’ll disappoint you. There is no magic formula aside from the age-old wisdom of differentiation and service.

Beating Time and Place
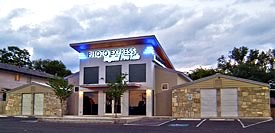
My friends at Digital Pro Lab in San Antonio are an excellent example of adjusting to change. What could be more outdated than a drive-up 30 minute film developing shop? What was formerly an epitome of time and place convenience (pictures in a half hour without getting out of your car), has become almost a caricature of “old school.”

Technology has shifted from celluloid film to digital. “Developing” now consists of uploading the files from your phone to a mega-printer who mails 8×10 prints overnight for less than Digital Pro’s cost. The photo chains, Ritz Camera, Fox Photo, and Wolf Photo are all gone, crushed by those “mail order, ” or perhaps more properly “email order” houses.
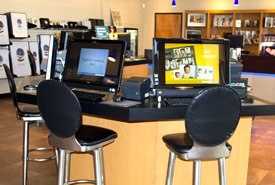
Digital Pro has survived (and thrives) by their differentiation and service. The large, bright showroom is full of computers where they can show customers the effect of adjusting color balance or editing. They can print your lifetime memories on almost anything, from a key chain to a large metal panel. They can still give you prints made with permanent liquid ink, not the water soluble powder used by most printers.

In addition, they can do all of this online because they’ve invested in the technology necessary to keep up with the “convenience-based” competitors.

As the cost of digital printers fell, professional photographers invested in their own machines. Digital Pro Lab has replaced their business with consumers who want to discuss their special moments, choose how to preserve them, and hold the results in their hands before they pay.

In an industry where the number of time and place based outlets has fallen by over 90% in the last decade, Digital Pro Lab has beaten the big boys with product differentiation and service. When the time comes for planning an exit, they will have options.

Do you know a business owner who will be exiting in the next ten years? Please share Awake at 2 o’clock!
Posted in Building Value, Entrepreneurship, Exit Options, Exit Planning, Marketing and Sales | Tagged , , , , , , , , , , , , , , | Leave a comment

Leave a Reply

Your email address will not be published. Required fields are marked *

The Unsellable Company

What does an unsellable company look like? Some business brokers will assert that there is a buyer for any business. That may be true, but historically four out of every five small businesses listed for sale fail to sell.

In this post I am specifically discussing profitable Main Street businesses. That is loosely defined as those valued at under $3,000,000. “Small” doesn’t necessarily refer to size. Some low margin businesses, such as those in distribution of commodity products, could have revenue well into eight figures and still be not command a $3 million valuation.

Others, like those with proprietary software, might have a few million dollars in revenue and be snapped up by a strategic buyer for an eight figure price.

The buyers for most Main Street businesses are individuals who are seeking a livelihood. They usually have never owned a business, and are betting their life savings on the venture. It’s not surprising that they are nervous.

The price ceiling on defining a Main Street company is based on the projected ownership. Simply put, if a business’ principle purpose is to provide an owner (or perhaps a few owners) with a decent standard of living, the ceiling on valuation is based on what the company’s cash flow can support in owner salary, debt service and ROI on the down payment.

To see if your presumed value supports these three requirements, try the Valuation Sanity Check at http://yourexitmap.com/exit-planning-valuation-sanity-check/.

Just because your cash flow justifies your price however, doesn’t mean your company is saleable (or as my Canadian friend John Warrillow writes it in Built to Sell, sellable.) There are still a number of reasons why a solidly profitable business may not find a buyer.

Owner Centricity

Simply put, the whole business revolves around you.  A buyer’s due diligence keeps running into you at the end of every question. How do you do this? (Ask Bob.) Who are your most important customers? (Ask Bob.) What discounts are available from your suppliers? (Ask Bob.) You get the picture.

Even if you have excellent processes, duplicable talents and widespread delegation, an owner who personally holds the professional license needed to legally operate presents a similar issue for a buyer.

Customer Concentration

Some small businesses are very good at what they do, but luck always plays a part. If you’ve grown by depending on one customer for over 50% or your business, or a handful of customers for 80%, expect individual buyers to shy away.

Long term relationships are great, but if they aren’t documented don’t expect them to carry much weight in a valuation. It’s one thing to be proud of doing business on a handshake. It’s another to bet your life savings on one.

Uncertain Revenues or Margins

If you have to explain your tax returns with “We have some good years and some bad years,” you will have a problem attracting buyers. They don’t have your confidence that a bad year will be followed by a good one. If they are committing their retirement savings to the purchase (which is often the case) they are worried about having the financial stamina to withstand a dip in sales.

Similarly, it you are regularly buttressing your revenues with cuts in margin through big discounts or volume deals, it will be perceived by a prospective buyer as regularly having to “save” the business.
You may have steadily increasing revenues and profits, but companies that bid, or have to submit proposals for each job, strike fear into the hearts of inexperienced buyers. They have nightmares about failing to win another job from the day they take over.

Contracts help with this, but they often aren’t enough. I worked with one buyer whose offer was based on the revenue stream from each existing contract until it expired. He wanted to be made whole for the purchase price even if he proved unable to ever land another big customer.

The Unsellable Company

If you recognize your business as having any of these traits, you have three choices when it comes to exit planning.

You can sell the company to employees who understand the constraints of the business and are comfortable with them. You can list the company for sale anyway, and hope that yours is among the 20% of enterprises for whom the right buyer can be found.

Finally, you can implement a plan to eliminate the obstacles to a sale.

Posted in Building Value, Exit Planning | Tagged , , , , , , , , , , , , , | Leave a comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Business isn’t Zero Sum

In any negotiation, you can assume a win-win solution or a zero sum outcome. “Win-win” is defined as when both parties come out ahead or achieve what they seek. “Zero sum” is when the premise behind negotiation is that whatever one party achieves equals a loss for the other.

Liberal economics (not the left-wing kind of liberal, the open-markets type) assumes that most trade is win-win.  For example, cheap Chinese labor and government subsidies allow working class Americans to walk around with powerful pocket computers (their smart phones). Who enjoys the greatest economic benefit?

Certainly the many thousands of Chinese workers enjoying a newly middle-class lifestyle are better off. So are the manufacturers and marketers (such as Apple) who profit as the middle men. But win-win economics argues that the value to everyone in the product pipeline pales in comparison to the economic stimulus of instant communications, Internet shopping and access to unlimited information.

On the other hand (a favorite phrase of economists everywhere), to the unemployed American worker who presumably would be making that phone, albeit at a much higher cost; it looks a lot like a zero-sum proposition.

When Wal-Mart began buying in China, economists calculated the net savings for Americans as equal to a 1% drop in the cost of living nationwide for the next several years. The millions of working class Americans who poured into Wal-Mart stores for cheaper goods might be shocked at an accusation that they were putting their neighbors out of work, but it was true.
Business is Win-Win

We accept win-win in business every day. You know that your vendor is profiting on what he sells you; that’s how he stays in business. You fully expect to profit from selling your goods and services. The people who buy them expect a benefit in proportion to what they spend, or they wouldn’t do business with you.

You pay your employees more if they are productive, meaning that in return they make you more money. Employers who worry that every dollar they pay in wages is one less in their pocket don’t attract top personnel, and usually don’t thrive in business.

The assumption that everything is zero sum is not only wrong, it is stupid. The political, social and business  landscapes can’t function on a premise that anything good for one party is automatically terrible for the other.

Allowing American companies to fill positions for which they can’t find Americans keeps them growing. As a point of information, those seeking H1B worker visas for technology workers can only do so if they have advertised the job to Americans, interviewed all qualified applicants, published the compensation, and agree to pay the same compensation whether the job is filled by an American or a guest worker. Those are the current requirements.

Saying that every guest worker has stolen an American job is ridiculous. Just as ridiculous is the claim that any controls over firearms leads inevitably to troops bashing down your door for general confiscation. So also is the position that every social safety net creates dependents who will mooch on the taxpayer for generations. Along with that put the premise that all foreign trade is evil because someone profits from it.

A Zero Sum Business

Let’s try running your business on zero sum assumptions. Set the amount you wish to pay for each expense item on your P&L. Determine your sales price for maximum profit. Then post wages that will get you the most return on your employees’ labor.

Now, announce that under no circumstances will you vary by one penny from what you want to pay or charge. Tell everyone that you aren’t in a position to lose anything just so they can win. Your vendors, customers and employees can take it or leave it.

Good luck.

Your Exit Map: Navigating the Boomer Bust is a fully-illustrated look at the impact of Baby Boomers on small business ownership, and what their options will be for transitioning companies.

You san sign up to receive free excerpts in advance of publication here.

Posted in Entrepreneurship, Management, Thoughts and Opinions | Tagged , , , , , , , , , , , , , , , , , , , | 1 Comment

One Response to Business isn’t Zero Sum

  1. Mike Wright says:

    Very good points. Unfortunately we have become very short term and self centered thinkers. Those with the greatest economic or political power will do what is necessary to gain and retain their control. This creates sub-optimal binary states that we fluctuate between rather than making long term gains for all.

Leave a Reply

Your email address will not be published. Required fields are marked *

Stop Managing

Why would anyone advise business owners to stop managing? Management is a proven science. From the time and motion studies of Frederick Winslow Taylor in the late 1800s, to Matthew Kelly and Patrick Lencione’s Dream Manager, we are constantly in search of ways to make employees more effective.

Management trends (some say “fads”) come and go. Wikipedia lists a number of major theories since the 1950s, including Management by Objectives, Matrix Management, Theory Z, One-minute Management, Management by wandering around, Total Quality Management, Business process reengineering, Delayering, Empowerment, 360-degree feedback, Re-engineering and Teamwork.

You could probably throw in a couple of offshoots like ISO 9000, Open Book Management, Six Sigma, Balanced Scorecards and Net Promoter Score. All have metrics (Key Performance Indicators) to measure their effectiveness.
In the 125 years since Taylor, after the introduction of automobiles, telecommunications, manned flight and the Internet, we are still working from the basic framework of time and motion studies. We try to empower people, but that often just means having them track their own production rather than have someone else do it for them. (Delayering)

That leads us to one of the Catch 22s of many business owners’ reality.  Once you have grown an enterprise large enough to require management, you’ve outgrown the skill set that made your business successful.

Small businesses become bigger businesses through their owners’ leadership and creativity. Time isn’t a fungible commodity, you can’t save it or get more of it. In a zero-sum  equation, any increase in one factor means a reduction in others. The more time you spend managing, the less there is left over for leading and creating.

Stop Managing, Start Creating

Last week, I sat in on a panel of three successful business owners who were discussing the value of a second in command. Each mentioned how delegating the management tasks of daily operations had freed them to focus on longer-term objectives, develop new ideas, and improve their personal quality of life. (In case you’ve forgotten, that’s why we own companies.)

A second-in-command to manage the business can’t be undervalued. I recommend Gino Wickman’s Rocket Fuel for a terrific examination about the relationship between a visionary and an implementer. If you haven’t read my own Hunting in a Farmer’s World, subscribe to Awake at 2 o’clock (to the right) for the chapter “I’m a little bit ADD” and see if you recognize yourself. (If you already subscribe, don’t worry. We don’t send duplicate emails.)

There were a number of owners from smaller businesses in the panel’s audience. Their comments were not unexpected. “I can’t afford a hire really top-flight manager.” “What if I get dependent on someone and he leaves?” “How can I find someone who knows as much about the business as I do?”

Those observations are being made by looking through the wrong end of the binoculars. The real question to ask  is “What would happen if I had more time to do what I do best?”

The average business owner estimates that about 20% of his or her time is spent in business development, the long-term creation of new products, services, systems and relationships. If a second in command can take just 30% of your duties, you could increase your business development effort by 150%.

What will happen if you stop managing, and devote 2 1/2 times the effort to growing your business? That’s how much a good manager is worth.

Are you over 50 years old, or do you advise business owners who are?

Sign up for free excerpts of my upcoming book, Your Exit Map: Navigating the Boomer Bust

Posted in Building Value, Entrepreneurship, Exit Planning, Leadership, Management | Tagged , , , , , , , , , , , , , , , , | 1 Comment

One Response to Stop Managing

  1. Ed Bierschenk says:

    Great summary of the panel session. I was in the audience for the panel and it was clear that business owners need to be more willing to let go and delegate more to a qualified 2nd in command. Like, John, I would encourage owners to consider upscaling their next hire into a more qualified candidate who can assume a strategic competency as a GM, Operations Manager, or even 2nd in-training. This is a high leverage investment which will allow more time for “working on the business.” TAB Business Coach-

Leave a Reply

Your email address will not be published. Required fields are marked *

Exit Planning in a New Political Environment

What does a new political environment mean for business owners who are planning to transition their businesses? Should you accelerate your plans, or slow them down?

As I’ve said many times in this space and elsewhere, the biggest single factor in successfully selling a company is the current condition of the financial markets. Since the Great Recession, the Federal Reserve has poured new cash into the system at very low interest rates. This “cheap money” has trickled down to fund a wave of leveraged buyouts by financial professionals seeking a better return than that from more traditional investments.

This wave of cash enables some 7,000 private equity groups (PEGs) to seek targets in almost every industry. Those targets, however, are typically among the 20,000 or so privately held companies with over $1,000,000 in pre-tax profit.

That leaves out some 9 million employers on Main Street (those that sell for less than $3,000,000.) Of those, about 5 million are owned by Baby Boomers who are, or should be, thinking about life after business ownership.

Most of the owners I talk to are at a loss to predict the climate of the next few years. They hope that a pro-business administration will reduce bureaucracy and pull back some of the regulatory burden on business owners. On the other hand, they are concerned that trade wars, rescission of treaties or diplomatic snafus will drive the US, or the world, into another economic trough.

A very few claim that they know exactly what President Trump and the Republican Congress will do. In the words of Prussian General Helmut von Moltke, “No battle plan survives contact with the enemy.” People may think they know what is coming, but it would be foolish to bet the ranch on any single outcome.
What does this mean for exiting business owners? At the risk of sounding too pat, it means exit planning is more important now than ever before.

Why Start Exit Planning Now?

Here are some reasons why an exit plan is valuable in uncertain times:

  • If your planned exit is more than five years from now, the landscape will likely change again before you transition. A plan will give you the tools to track key components of a successful exit, and improve your ability to respond to changes.
  • If your intention is to preserve the legacy of your company by selling it to employees or family members, starting the transfer now can put you in a position to accelerate or delay the final transfer according to current conditions.
  • If the stated intention of the new administration (a return to 4% GDP growth) is successful, a plan to maximize your value to a third-party buyer will leverage higher pricing multiples.
  • If the economy winds up in the tank, a plan is only a plan. It can always be put on hold until conditions improve.

An exit plan is, by definition, a strategic plan with the addition of a completion date. Some owners fear that by stating a deadline, they are committing to it regardless of circumstances. Of course that isn’t true.

Planning your exit and actually exiting are two different activities. It only makes sense that the political environment should be one of the factors that affect your final decision.

Would you like free excerpt from my new book Your Exit Map: Navigating the Boomer Bust?

Just register here. We’ll send you short pieces every few weeks until its publication in the Spring.

Posted in Exit Planning, Exit Strategies | Tagged , , , , , , , , , , , , , , , , , , , , , , | Leave a comment

Leave a Reply

Your email address will not be published. Required fields are marked *